A prequalification questionnaire can now reveal as much about a contractor’s environmental controls, labor practices, and governance discipline as it does about project experience. For construction and industrial firms, ESG compliance trends are no longer confined to annual sustainability reports prepared by large corporations. They are increasingly influencing tender eligibility, client audits, financing decisions, supplier selection, and day-to-day site controls.
The practical challenge is that ESG requirements rarely arrive as one clear standard. A main contractor may request carbon data and worker welfare evidence, while an investor, lender, or public-sector client expects formal governance oversight and documented risk management. Companies that treat each request as a one-off administrative exercise can quickly create inconsistent records, duplicate work, and expose gaps during review.
For operational leaders, the priority is not to create a polished ESG narrative first. It is to build reliable evidence from the systems that already govern safety, quality, environmental performance, subcontractor management, and leadership accountability.
ESG Compliance Trends Moving Into Operations
The strongest ESG trend is the shift from voluntary statements to verifiable performance. Customers, procurement teams, and other stakeholders increasingly want to see source records, assigned responsibilities, measurable objectives, and evidence that corrective actions have been closed. A policy on its own carries limited weight if the company cannot show how it is applied on projects.
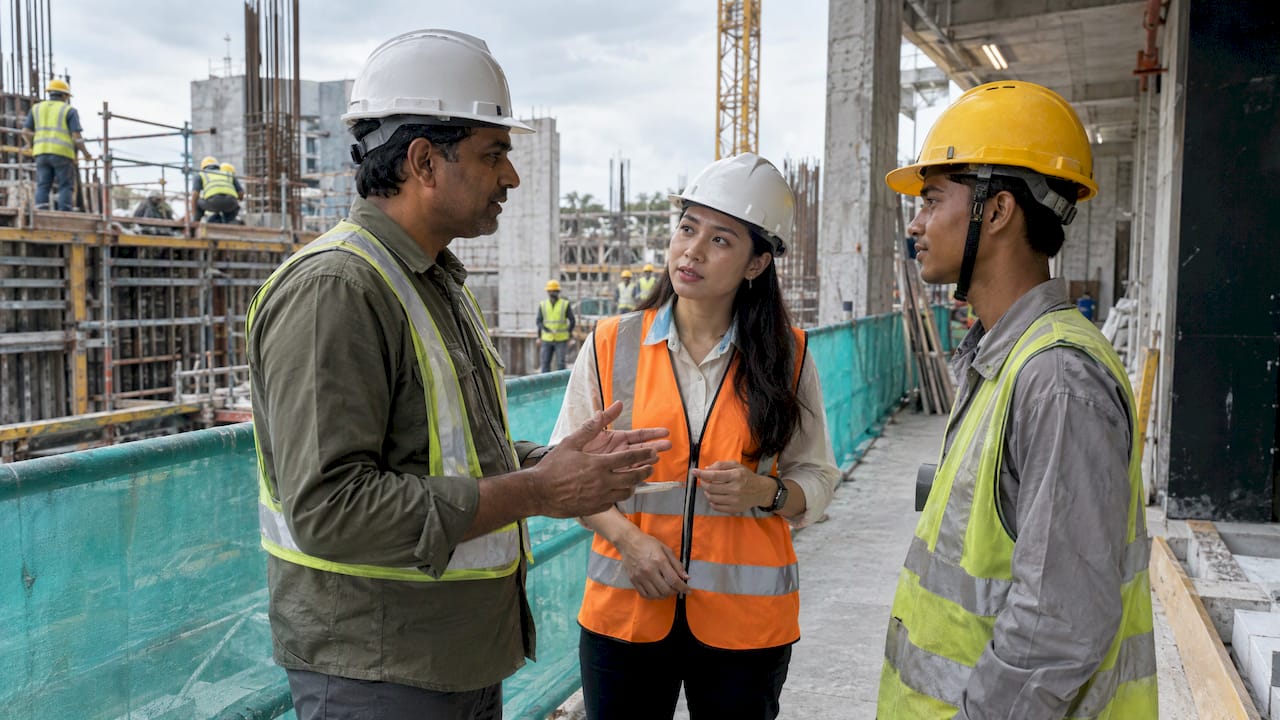
This shift is especially relevant in construction, where material waste, energy use, worker safety, labor practices, and subcontractor conduct can vary significantly from site to site. Project controls must be consistent enough to support company-level reporting, yet practical enough for supervisors and subcontractors to follow under real site conditions.
Environmental data is becoming more specific
Environmental disclosure is moving beyond broad commitments to reduce impact. Organizations are being asked to account for energy consumption, fuel use, waste streams, water use, material sourcing, and, where relevant, greenhouse gas emissions. In construction, clients may also ask how a contractor manages dust, noise, spills, hazardous substances, disposal vendors, and environmental incidents.
The right level of detail depends on the contract, company size, and reporting obligation. A smaller specialist subcontractor may not need the same emissions inventory as a multinational developer. However, it still needs organized records that can support client requests. Fuel logs, waste transfer documentation, environmental inspection reports, equipment maintenance records, and incident investigations provide a far stronger starting point than estimates prepared after the project ends.
Environmental data must also be governed. Define who collects it, where it is stored, how often it is reviewed, and who approves the final figures. A spreadsheet can be suitable for an early-stage program, but only if version control and ownership are clear. As reporting demands grow, disconnected spreadsheets become a source of error rather than a solution.
Social performance is closely tied to site management
In safety-sensitive industries, the social element of ESG is not separate from workplace practice. It includes occupational health and safety, fair employment, training, worker accommodation where applicable, grievance handling, emergency readiness, and the treatment of subcontracted labor.
Leading clients are looking beyond a companywide injury rate or training register. They may assess whether risk assessments are current, whether workers understand the controls, whether near misses are investigated, and whether supervisors have authority to stop unsafe work. They may also review working hours, worker welfare arrangements, competency records, and mechanisms for raising concerns without retaliation.
This creates an important trade-off. Collecting more social data can improve visibility, but excessive reporting requirements can burden site teams and reduce data quality. The better approach is to integrate ESG-relevant measures into existing EHS processes. Daily briefings, inspections, toolbox talks, training matrices, incident reports, and corrective-action registers should produce useful evidence as part of normal operations, not as a separate reporting burden.
Governance is being tested through accountability
Governance can sound remote from construction operations, but it is often where ESG programs succeed or fail. Clients and auditors increasingly examine who is responsible for ESG matters, how leadership reviews risks, how conflicts of interest are managed, and whether suppliers are screened against clear criteria.
For a contractor or engineering firm, governance evidence may include a defined management structure, documented delegation of authority, ethical conduct policies, procurement controls, internal audit findings, management review minutes, and a process for reporting and resolving concerns. The goal is not unnecessary bureaucracy. It is to show that decisions affecting people, environmental performance, and business integrity are subject to oversight.
Boards and senior leaders do not need to manage every site record. They do need periodic, meaningful information: serious incidents, recurring nonconformities, major environmental events, supplier risks, overdue corrective actions, and progress against agreed objectives. When leadership review is documented, ESG accountability becomes visible to clients and assessors.
How ESG Compliance Trends Affect Procurement
Procurement is one of the fastest routes through which ESG expectations reach contractors. Tender documents increasingly include supplier codes of conduct, safety performance questions, environmental commitments, diversity or labor requirements, and requests for certifications or policy documents. A contractor that cannot respond consistently may lose opportunities before commercial or technical capability is fully evaluated.
The risk is not limited to bidding. Once awarded, companies may face periodic client scorecards, site audits, and requests for evidence from lower-tier subcontractors. If subcontractor controls are weak, the principal contractor can still face reputational and contractual consequences.
A practical supplier management process should establish minimum requirements before work begins. These may cover safety competence, legal eligibility, insurance, environmental controls, incident reporting, worker welfare, and agreement to the company’s code of conduct. The depth of screening should reflect the risk. A high-risk subcontractor handling hazardous materials deserves more detailed review than a low-risk office services vendor.
Contractual requirements also need to be communicated in operational language. A clause requiring compliance with environmental and labor expectations has little effect if procurement staff, project managers, and subcontractor supervisors do not understand the records and behaviors expected on site.
Building an Evidence-Ready ESG Program
An effective ESG compliance program starts with a focused gap assessment. Review current policies, certifications, EHS records, procurement procedures, training, leadership oversight, and project documentation. Then compare them with the requirements that matter most: legal obligations, client expectations, lender requirements, and sector-specific risks.
Avoid beginning with a long list of generic ESG indicators. Construction firms should prioritize material issues that can be controlled and evidenced. Worker safety, environmental incident prevention, waste management, legal compliance, subcontractor oversight, ethical procurement, and competency management are often more useful starting points than broad claims that are difficult to substantiate.
From there, establish a manageable set of metrics. Useful measures may include recordable incidents, near-miss reporting, corrective-action closure, safety training completion, waste diversion, fuel use, environmental nonconformities, supplier assessments, and ethics training. Each metric needs a definition, data owner, reporting frequency, source record, and review process. Without these controls, a number may look credible but fail under audit.
Documentation should be proportionate. An SME does not need to replicate the reporting infrastructure of a listed global company. It does need a clear policy framework, credible records, and accountable management. ISO-based management systems can provide a practical foundation because they already support risk assessment, documented processes, performance monitoring, internal audits, corrective action, and management review.
Independent audits and site inspections add value when they test implementation rather than merely checking whether documents exist. An audit should identify where procedures are not understood, where evidence is incomplete, and where controls break down under site pressure. The resulting action plan should assign owners and deadlines, then be tracked to closure.
Common ESG Compliance Mistakes to Avoid
One common mistake is overstating performance. Claims about sustainability, safety culture, ethical sourcing, or carbon reduction should be supported by current data and defined boundaries. Overly broad statements can create reputational risk when clients ask for evidence.
Another is treating ESG as the sole responsibility of one sustainability or compliance officer. EHS, procurement, human resources, finance, project delivery, and senior leadership all hold part of the evidence base. A single coordinator can guide the program, but operational owners must remain accountable for their data and controls.
Companies also underestimate the time needed to improve data quality. Historical records may be incomplete, project reporting may vary, and subcontractor information may not be readily available. It is better to disclose a defined baseline and improvement plan than to rush unsupported figures into a client submission.
For construction and industrial organizations, ESG maturity is built one controlled process at a time. Start with the risks that are already visible on your sites, assign clear ownership, and make evidence collection part of normal management practice. That is how ESG requirements become a source of operational discipline rather than another last-minute compliance exercise.